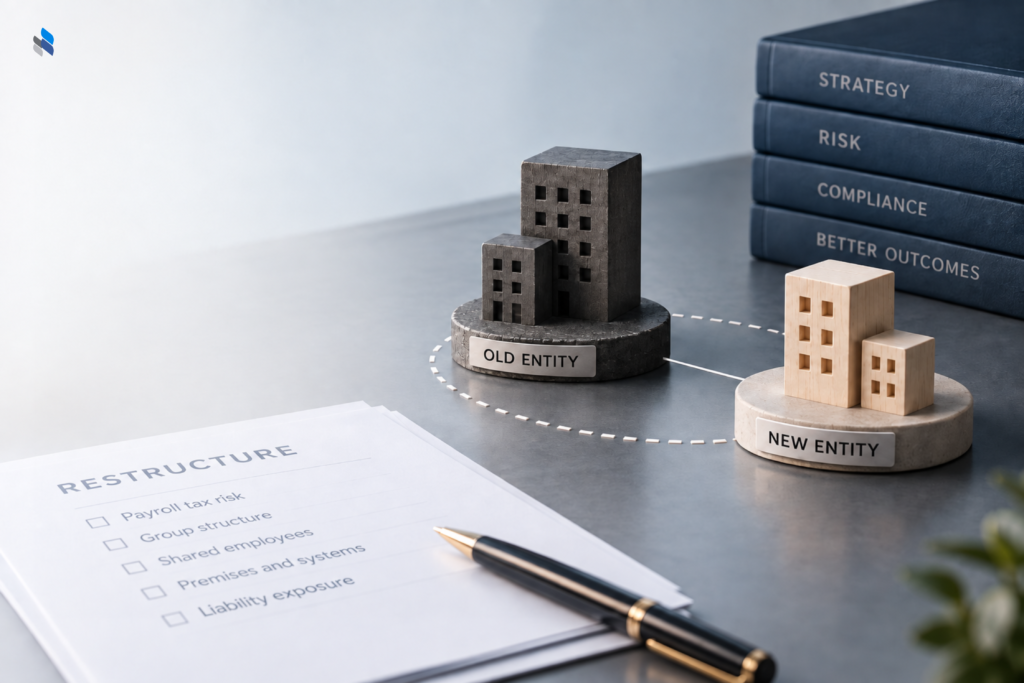
When a client restructures out of a struggling company into a new entity, payroll tax grouping is the exposure most likely to follow them across, and it is rarely on the checklist. Grouping lets a state or territory revenue office treat two or more connected businesses as a single unit for payroll tax. Once that happens, the entities share one tax-free threshold and, critically, each becomes jointly and severally liable for the whole group’s payroll tax debt.
How Payroll Tax Grouping Works
Payroll tax is a state and territory tax on wages. Grouping provisions allow the revenue office to combine the wages of connected businesses and assess them as one. Businesses can be grouped where they are related bodies corporate, where they use common employees, where they are commonly controlled, or where a controlling interest can be traced from one to another. The tests are broad, and they are applied to substance rather than labels.
It Is Not Only a Restructure Issue
Grouping does not require any intention to avoid payroll tax. It can arise simply because two businesses a client controls share an employee, or because a family group runs several entities that each sit under the threshold on their own. Professional and medical practices are a current area of focus, where service entities, common staff, and shared administration can pull separate practitioners into a single group. The outcome is the same in every case: one tax-free threshold across the whole group, and shared liability for the group’s debt. A client can be exposed without ever having restructured anything.
Why It Bites Hardest in a Restructure
Grouping is a live risk exactly when a client is trying to move on from a failed entity. If the new business shares staff, premises, the same accountant, similar officeholders, a common trust, or even a reused website with the old one, the revenue office can treat the two as grouped. The consequence is that the old entity’s payroll tax liability can attach to the new one, undoing the restructure the client thought they had completed.
A family cleaning business with about 60 staff had traded for 15 years. After a major debtor failed to pay, cashflow collapsed, and the owners restructured, transferring the business to a dormant company they already held and liquidating the original entity. Fourteen months on, the state revenue office deemed the two entities grouped, pointing to the shared workforce, premises, accountant, registered office, similar officeholders, common trust beneficiaries, and a reused website. Around $850,000 of the old company’s payroll tax debt attached to the new entity, which made it technically insolvent despite an otherwise clean restructure.
What to Check Before a Restructure
Before a client moves to a new entity, the grouping risk is manageable if it is addressed early:
- Avoid using a dormant company the client already owns as the purchaser
- Establish genuinely distinct officeholder and control structures
- Wind up associated trusts at the same time rather than leaving them in place
- Separate premises, staffing arrangements, and branding where practical
- Confirm the old entity’s payroll tax position before the transfer, not after
The Value of Acting Early
Grouping decisions are difficult to unwind once the revenue office has formed a view. The time to deal with it is at the planning stage. de Jonge Read® develops the restructure strategy, project manages the moving parts, coordinates with the client’s accountant on the payroll tax position, and engages the appropriate practitioner where a formal process is required. The aim is a restructure that holds, not one that collapses under a debt the client believed they had left behind.
If you have a client considering a restructure and there is any history of payroll tax debt, it is worth a conversation before the new entity starts trading. de Jonge Read® works alongside you to structure the move so grouping does not follow the client across. Contact the team on 1300 765 080 for a confidential, obligation-free discussion.
Should you have clients or associates that you know are struggling with financial issues or need assistance in reviewing their business affairs in preparation for what’s around the corner, our team of Strategists would be pleased to discuss options that are available on how to best design and implement insolvency strategies. Contact us now on p. 1300 765 080 | ua.moc.arjd@ofni
Did you know?
Phoenixing is another name of business restructure. Read more about business restructures and when this can be an option for you.